


The Complete Guide to B2B Cross-Border Payments

Efficient cross-border transactions are a pre-requisite for businesses to enter global markets and to scale across them.
Yet cross-border payments can become more complex as they move between different financial institutions, currencies, compliance requirements and local payment systems. This can create longer settlement journeys, reduced visibility into payment status, additional costs and varying payment experiences across markets.
Modern payment infrastructure is transforming B2B cross-border payments. Solutions like the Thunes Direct Global Network allow businesses to seamlessly connect to local payment networks worldwide, unlocking faster settlement, greater transparency, and an accelerated go-to-market for businesses expanding across global markets.
This guide explores modern B2B cross-border payments, the opportunities and challenges they create and how Thunes’ Direct Global Network helps businesses move money globally with greater reliability, transparency and speed.
Table of contents
What are B2B cross-border payments?
B2B cross-border payments involve one business transferring money to another business in a different country, often using a different currency. They enable organisations to pay suppliers, distributors, partners and service providers worldwide, supporting everything from international trade and procurement to local payroll.
They are the lifeblood of the global economy. In 2024, the B2B cross-border payments market accounted for $31.6 trillion and is predicted to grow by 58% to $50 trillion in 2032.
Sending payments between businesses in different countries
While the concept is straightforward, the complexity should not be underestimated, with the businesses, payment methods and infrastructure behind these transactions having evolved significantly in recent years.
Unlike consumer payments, B2B cross-border payments typically involve larger transaction values, more complex approval processes, and stricter regulatory requirements. A single payment may pass between multiple financial institutions, involve foreign exchange conversion, and require multiple compliance checks before reaching the recipient.
Use cases for cross-border business payments include:
- Paying international suppliers and manufacturers
- Settling invoices with overseas partners
- Paying business service providers
- Moving funds between international entities
Whether a business is paying a supplier in Germany or a manufacturer in Brazil, the objective is the same: moving money securely, efficiently and reliably across borders.
Why modern B2B cross-border payments are becoming more complex
Expanding internationally creates new opportunities, but it also increases payment complexity. Businesses are no longer sending funds only between bank accounts in major global financial centres, and payment chains can now involve:
- Local banking networks and real-time payment systems
- Multiple currencies and foreign exchange cost pressures
- Country-specific regulations and compliance requirements
- Different clearing and settlement infrastructures
Supporting this payment infrastructure market by market is difficult without the right infrastructure. Businesses need solutions that simplify connectivity, manage compliance and foreign exchange, and provide reliable access to local banking infrastructure across global markets.
How modern B2B cross-border payments actually work
Cross-border payments have traditionally relied solely on correspondent banking networks to move money between countries.
While that infrastructure remains an important part of the global financial system, B2B cross-border payments increasingly draw on a broader mix of banks, APIs, local payment rails and routing technologies to support payments across different markets and payment environments.
The traditional cross-border payment journey
For decades, most B2B cross-border payments followed a similar path. A payment would move from the sender’s bank through one or more correspondent banks before reaching the recipient’s financial institution.
Traditional payment journey: Business → Sending bank → Correspondent bank(s) → Receiving bank → Recipient
The trade-off is that additional intermediaries can increase processing time, operational complexity and costs, with settlement times varying depending on the countries, currencies and banking relationships involved.
How modern payment infrastructure changes the journey
Modern payment infrastructure builds on existing banking networks rather than replacing them. Payment providers connect businesses to multiple payment networks through a single integration, intelligently selecting the most appropriate route for each transaction.
Modern payment journey: Business → Payment platform/API → Intelligent routing → Local banking network → Receiving business bank account
Businesses integrate once, while payment platforms orchestrate connectivity behind the scenes to route payments through the most appropriate banking and payment infrastructure in each market.
This approach also improves interoperability across the payments ecosystem.
| Traditional approach | Modern approach |
|---|---|
| Relies primarily on correspondent banking networks | Connects multiple payment networks through a single platform |
| Payments may pass through multiple intermediaries | Intelligent routing selects the most appropriate payment path |
| Primarily supports correspondent bank transfers | Supports local banking networks through a single connection |
| Settlement times vary depending on the payment route | Faster settlements where supported by local infrastructure |
| Businesses may need multiple market-specific integrations | Single API connection provides access to multiple markets |
For businesses, the result is greater flexibility in how payments are routed, improved visibility across payment flows and simpler access to local banking infrastructure.
Benefits of modern B2B cross-border payments
Modern payment infrastructure does more than move money between countries. It helps businesses expand into new markets, simplify international operations and deliver payment experiences that meet growing customer and partner expectations.
Expand into new international markets
Entering new markets no longer means relying solely on correspondent banking relationships. Businesses need reliable access to domestic banking systems, local clearing networks and payment infrastructure that support commercial transactions in each market.
Modern cross-border payment infrastructure simplifies expansion by providing access to multiple markets through a single integration, reducing the complexity of connecting to different banking networks and regulatory environments on a country-by-country basis.
Improve payment speed and transparency
Payment speed remains an important consideration for businesses managing international suppliers, partners and customers. Modern payment infrastructure reduces unnecessary routing where possible, helping deliver funds more efficiently while providing greater visibility into payment status.
Improved transparency also makes it easier to monitor payments, manage exceptions and provide more accurate delivery expectations across international transactions.
Support local payment infrastructure
Commercial payments rely on different banking systems and domestic payment infrastructure in every market. Supporting these local networks without building and maintaining separate integrations is one of the biggest operational challenges for businesses expanding internationally.
By connecting to local banking infrastructure through a single platform, businesses simplify their cross-border payment operations by reducing the burden of managing multiple banking relationships and bespoke technical integrations.
Simplify global payment operations
Managing international payments across multiple countries often creates operational complexity as businesses grow. Modern payment platforms help simplify connectivity, compliance, foreign exchange and payment routing through a single platform, reducing the need to manage multiple providers and integrations.
This allows businesses to scale international payment operations more efficiently while maintaining a consistent payment experience across global markets.
The trends shaping B2B cross-border payments
The future of B2B cross-border payments is being shaped by three interconnected trends: real-time payments, increasing sophistication of local banking infrastructure, and growing interoperability across the global payments ecosystem.
Real-time payments are the new expectation
By 2032, the real-time payments market will reach $176.5 billion at a compound annual growth rate (CAGR) of over 27.5%.
Businesses no longer see faster cross-border payments as a competitive advantage. They expect international payments to offer the same speed, transparency and visibility as domestic transactions. As real-time payment systems expand and payment providers connect to these networks, international payments are becoming faster and more predictable.
While settlement times still depend on the countries, currencies and payment methods involved, modern payment infrastructure is helping reduce delays and improve liquidity management across global operations.
Local banking infrastructure is becoming more interconnected
Businesses expanding internationally need access to domestic banking systems and payment infrastructure across multiple markets. Rather than establishing separate banking relationships and technical integrations in every country, organisations are looking for simpler ways to connect to local payment ecosystems through a single provider.
This shift is driving greater investment in payment infrastructure that brings together local banking networks, clearing systems and cross-border connectivity. By reducing the complexity of accessing multiple markets, businesses can scale international payment operations more efficiently while maintaining consistent processes across their global footprint.
Interoperability is connecting global payment ecosystems
Rather than replacing existing financial infrastructure, the industry is focused on connecting it. Banks, payment providers and financial institutions are working towards greater interoperability through technologies such as APIs and global messaging standards, including ISO 20022.
By making different payment systems work together more effectively, businesses can access broader payment coverage, improve data quality and simplify international payment operations as they expand into new and emerging markets.
Challenges of B2B cross-border payments
Modern payment infrastructure has addressed many of the traditional challenges associated with cross-border payments.
However, businesses operating internationally still need to navigate regulatory complexity, foreign exchange and fragmented banking infrastructure across global markets.
Regulatory and compliance complexity
Every market has its own regulatory requirements, sanctions screening, AML obligations and payment rules. As businesses expand internationally, meeting these requirements across multiple jurisdictions becomes increasingly challenging.
Thunes ensures transactions adhere to local regulations and global compliance across many regions:
- USA: Thunes is a Certified Money Service Business with FinCen and holds a Money Transmitter License in Washington State.
- France: Thunes holds a Payment Institution License from Autorité de Contrôle Prudentiel et de Régulation (ACPR).
- EU: Extension of French Payment institution license.
- UK: Thunes is an Authorised Payment Institution by the UK’s Financial Conduct Authority.
- Singapore: The Monetary Authority of Singapore issued Thunes as a Major Payment Institution.
- Hong Kong: Thunes holds a Money Service Operator License by the Hong Kong Customs and Excise Department.
Foreign exchange and currency management
Cross-border payments often involve multiple currencies, exposing businesses to exchange rate fluctuations and varying conversion costs. As payment volumes grow and businesses expand into more markets, managing foreign exchange becomes increasingly important for controlling costs and improving cash flow visibility.
Thunes helps reduce this complexity through SmartX Treasury, which provides transparent FX pricing, locks exchange rates for a defined period and helps businesses manage liquidity more efficiently across global payment operations.
Managing fragmented banking relationships
As businesses expand internationally, they frequently need to establish banking relationships and technical connectivity across multiple markets. Each country may have its own banking infrastructure, clearing systems, payment standards and operational requirements, creating additional complexity as global operations grow.
Over time, this fragmented landscape can increase operational overhead, reduce visibility across payment flows and make it more difficult to maintain consistent payment processes across international markets.
B2B cross-border payments made simpler with Thunes
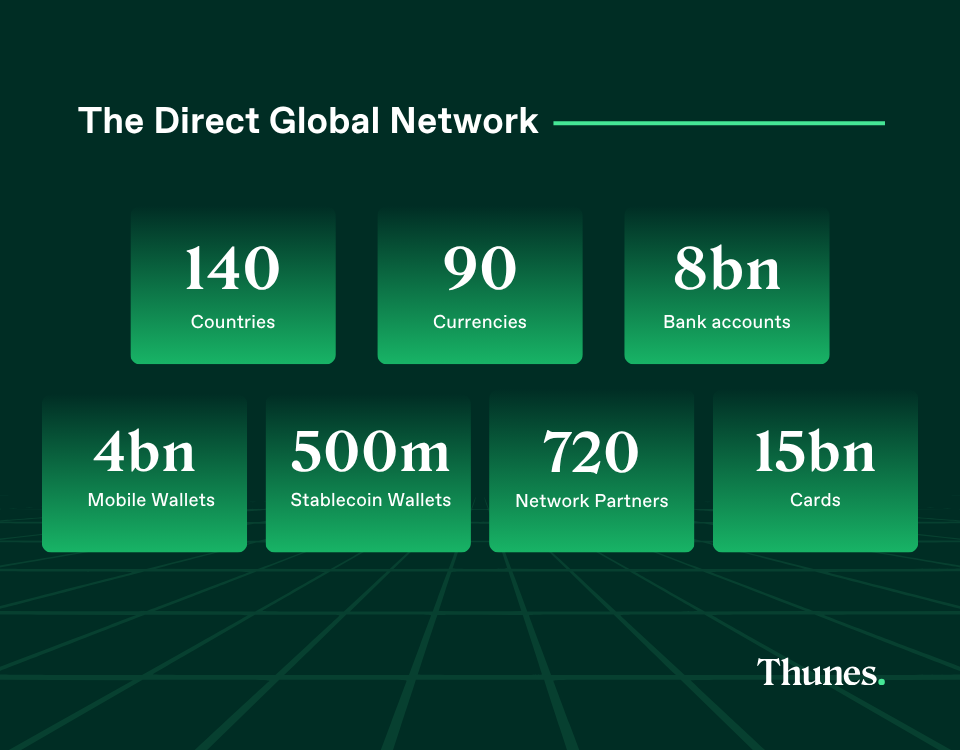
Modern B2B cross-border payments require global infrastructure that combines reach, local connectivity and operational simplicity.
Thunes is the Smart Superhighway to move money around the world. With a single API, Thunes connects businesses to its Direct Global Network, giving them access to:
- 140 countries through one global connection
- 90 currencies across global markets
- 8 billion bank accounts
- 720 direct network partners, enabling intelligent routing across global and local payment infrastructure
- Fast, reliable and transparent payments with real-time tracking and predictable pricing
Whether you’re entering new markets or scaling international operations, Thunes helps businesses simplify global payments through one trusted network.
Ready to simplify your global payment operations? Contact us today to see how Thunes helps businesses move money globally with reliability, transparency and speed.


