Unlocking Cross-Border Opportunity through Collaboration and Trust

Cross-border payments power the global digital economy. Today, as innovation accelerates across the payments ecosystem, speed, trust, and interoperability are redefining how money moves worldwide.
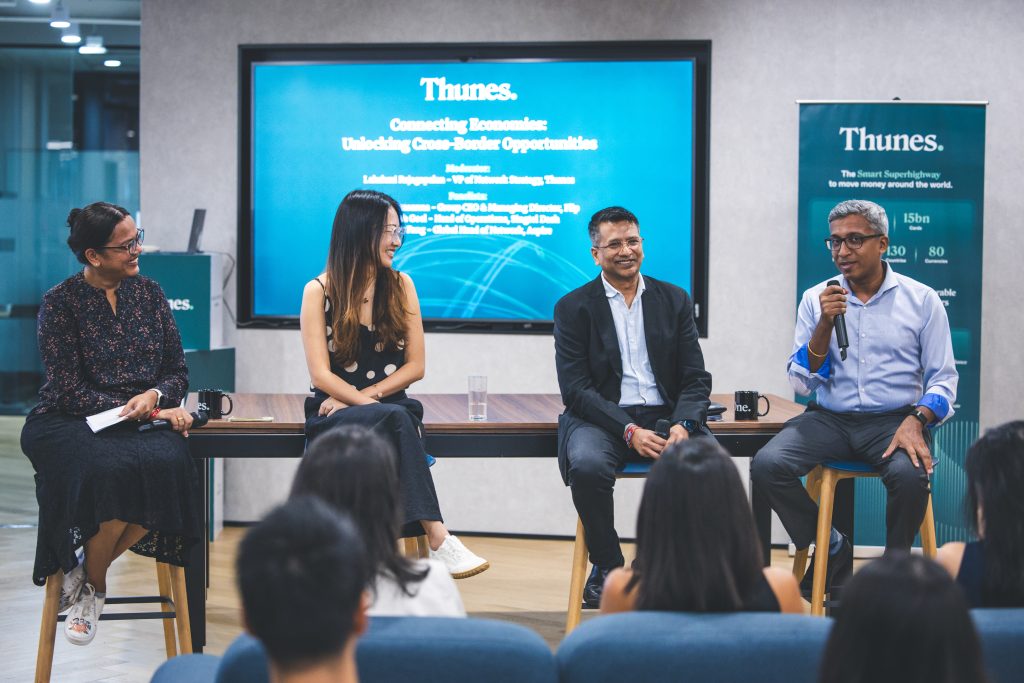
At the recent Thunes Meetup in Singapore, industry leaders came together for a panel discussion titled ‘Connecting Economies: Unlocking Cross-Border Opportunities’ to explore how collaboration, regulation, and technology are reshaping the future of payments. Moderated by Lakshmi Rajagopalan, VP of Network Strategy at Thunes, the session brought together Holly Fang, Global Head of Network, Aspire, Pratyush Prasanna, CEO, Flip, and Mahesh Goel, Head of Operations – Financial & Lifestyle Services, Singtel Dash, to explore how these forces are reshaping the future of payments.
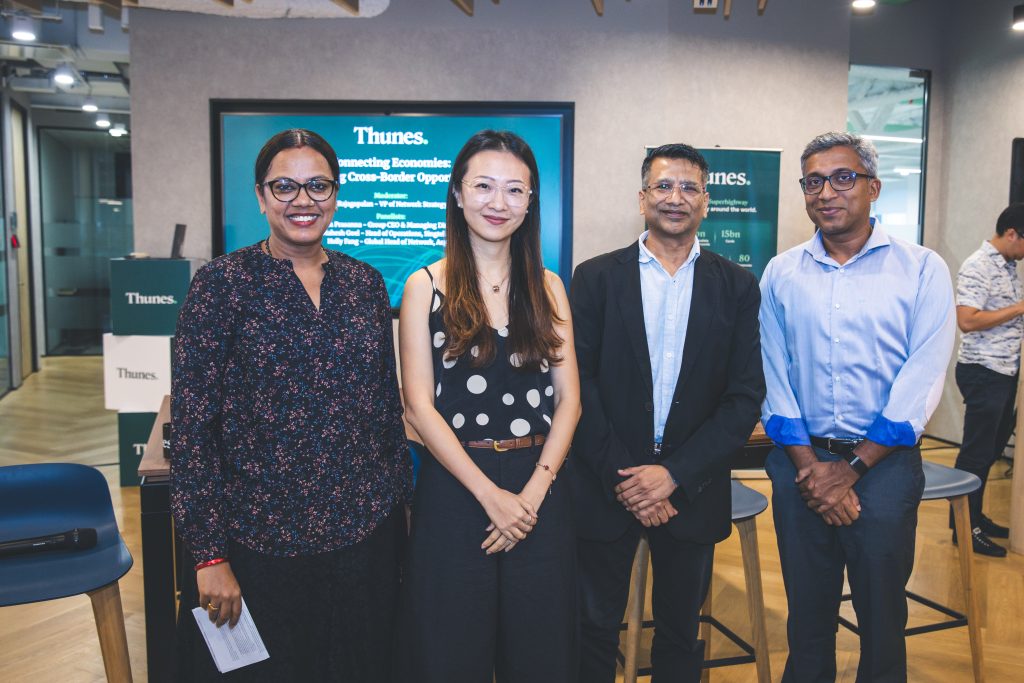
Their discussion revealed a clear message: the future of global payments will be shaped by collaboration rather than competition. Success in cross-border finance depends on trusted collaboration, progressive regulation, and inclusive design that puts people at the centre. Here are the key insights from their discussion on building a faster, more connected, and inclusive global payments ecosystem.
Fast, cost-effective payments in a connected world
Digital finance has advanced rapidly over the past three years. Businesses and consumers now expect payments to be instant, transparent, and affordable, no matter where they are.
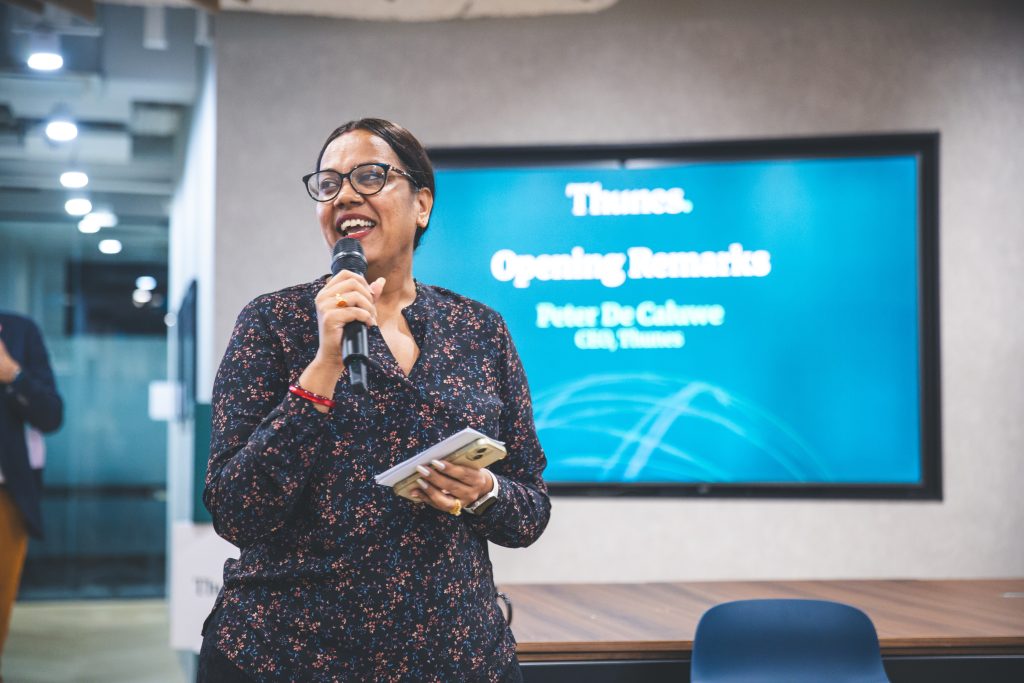
“The way we define ‘fast’ has changed,” said Lakshmi, opening the session. “What used to take days now feels slow if it takes more than a few seconds. Customer expectations are driving a complete rethink of how we design financial connectivity.”
That rethink is already underway across the industry. For fintechs like Aspire, which supports small and medium-sized businesses expanding internationally, the shift has meant rebuilding how payments work behind the scenes.
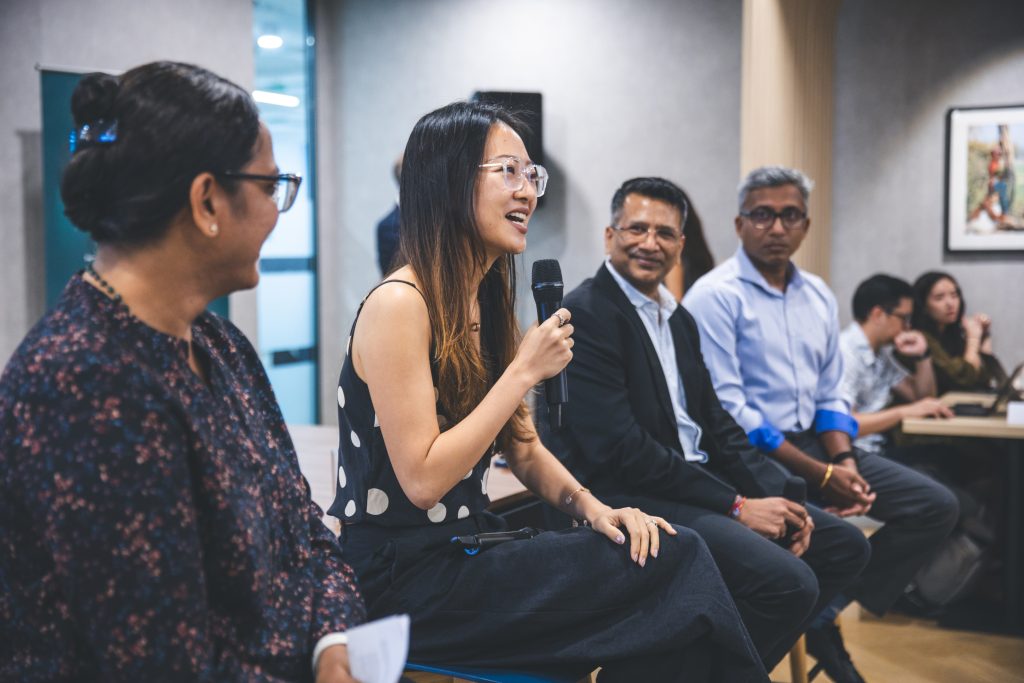
“Our clients are scaling beyond their home markets, and they need infrastructure that can scale with them,” said Holly. “An SME in Singapore should be able to pay a supplier in Vietnam or Europe as easily as making a local transfer; that’s the level of simplicity businesses now expect.”
She added that achieving that kind of global reach depends on strong partnerships. “You can’t build global coverage alone. Connecting to the right network partners allows us to deliver reliability, speed, and transparency; three things customers value above everything else.”
Balancing innovation and compliance
Scaling cross-border payments means more than just adding new corridors. It requires navigating layers of regulation, managing FX volatility, and integrating with legacy systems that weren’t designed for today’s speed.
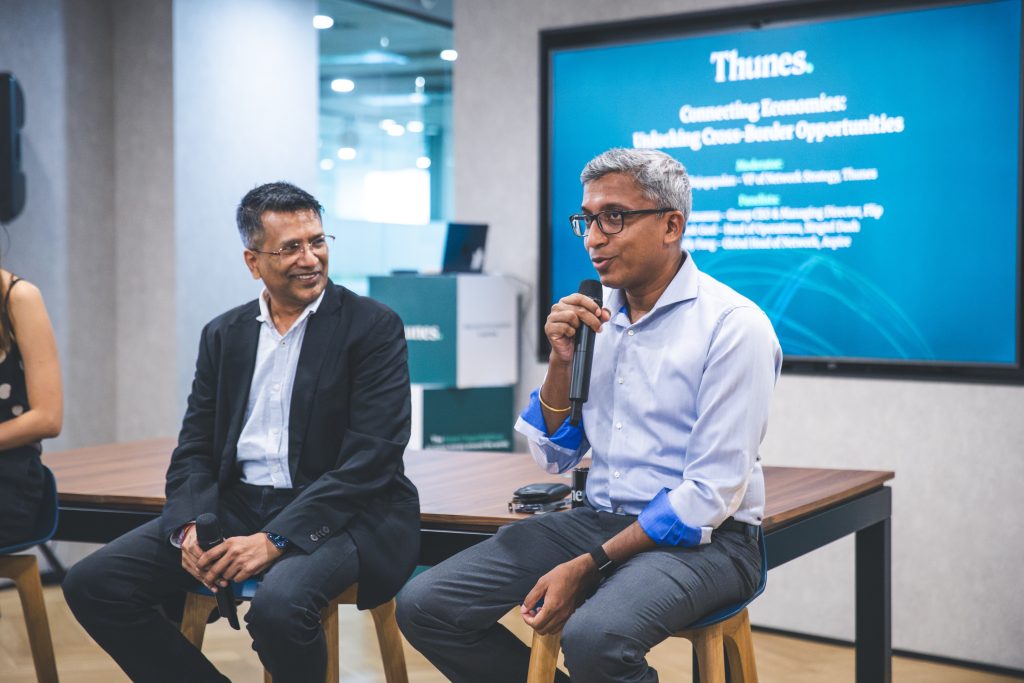
As the conversation turned to how innovators balance growth with governance, Pratyush from Flip reflected on the company’s evolution. “When we started, our goal was simple: to make transfers between banks in Indonesia faster and more affordable,” he said. “But as we grew, reliability and compliance became just as important as speed.”
Indonesia’s payment ecosystem has changed dramatically in recent years, with instant transfers now the norm across hundreds of banks and wallets. However, expanding national borders brought new complexities. “Every market has its own rules, its own regulators, its own expectations. Working with trusted partners who already have that local experience helped us move faster without compromising on governance.”
That balance of innovation and compliance echoes a broader truth shared throughout the panel: success in cross-border finance depends as much on relationships as on technology. As Lakshmi summed it up, “When we talk about connecting economies, we’re really talking about connecting capabilities. Each player brings something unique – local trust, regulatory clarity, or technology depth – and together they create a network no one could build alone.”
Designing for inclusion from the start
Inclusion remains a central principle in digital finance, and it’s evolving beyond affordability to encompass accessibility and trust.
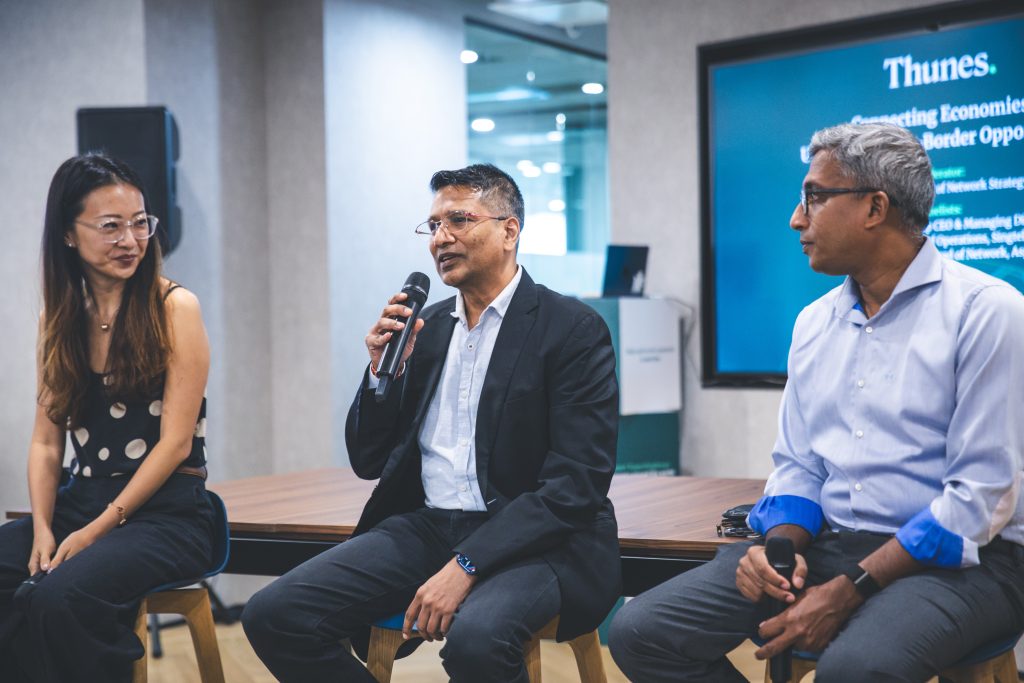
As Mahesh of SingTel Dash shared, “Beyond low fees, inclusion means accessibility. We serve customers who may not have high financial literacy or English as a first language. So we focus on building trust through multi-language support, simplified onboarding and education on safe digital usage.”
He noted that inclusion begins long before any transaction takes place. “People use what they trust. To build that trust, you must be visible in their communities, speak their language, and make every step, from registration to payout, simple and transparent.”
This perspective underscores a broader shift in financial innovation: true inclusion isn’t just about reaching more people, but about designing with empathy from the start and creating systems that meet people where they are, and grow with them.
Partnership as the new infrastructure
As the payments landscape evolves, the line between competition and collaboration is fading. Instead of replacing banks or fintechs, ecosystem players are co-creating shared infrastructure that connects them.
“The next phase of cross-border growth isn’t about owning the network,” said Holly. “It’s about interoperability and making sure systems talk to each other so that end users get a seamless experience.”
That interoperability depends as much on regulation as on technology. “Progressive regulators make all the difference,” said Pratyush. “Indonesia’s central bank has been forward-looking in defining standards for open APIs and digital remittances. That clarity allows fintechs to innovate responsibly and at scale.”
Holly noted that Singapore’s regulatory approach exemplifies this balance, encouraging experimentation while maintaining strong consumer protection, while Mahesh emphasised the human impact of consistency. “For migrant workers, regulation isn’t abstract, it’s what keeps their money safe. When customers know their transfers are licensed and compliant, adoption rises naturally.”
Together, their perspectives highlight a new reality: in cross-border finance, partnership itself has become the infrastructure built on trust, interoperability, and shared responsibility.
Connecting the world through trusted infrastructure
The discussion made one thing clear: the next phase of cross-border payments will be shaped by the convergence of systems, networks, and vision. Real-time infrastructures, digital wallets, and alternative payment rails are beginning to interconnect, forming a global financial network that moves value as effortlessly as data.
As this ecosystem matures, the focus will shift from the mechanics of transactions to the experience itself. Payments will simply be payments: instant, transparent, and trusted, no matter where they start or end. Behind that simplicity lies the invisible architecture built on collaboration: shared infrastructure, open standards, and clear regulation that enable scale without compromising security.
Inclusion will remain the industry’s common purpose. The future belongs to those designing systems that serve people – from SMEs expanding across borders to the next billion users entering the digital economy.
The journey towards real-time, borderless finance cannot be achieved in isolation. Its success depends on connection between partners, technologies, and regulators working in concert. Thunes and its network of collaborators exemplify this principle, proving that trust and partnership are not just catalysts for progress, but the foundation of a more connected financial world.
Let’s build the future of borderless payments together. Get in touch with Thunes to discover how seamless global transactions can transform your business.